CREATORS OF THE COMPLIANCE TUNE-UP®

AARMR | ABA | ACAMS | ALTA | ARMCP | IAPP | IIA | MBA | MERS® | MISMO | NAMB

Showing posts with label YSP. Show all posts

Tuesday, May 10, 2011

TILA Examination Procedures - Revised!

On May 2, 2011, the Office of Thrift Supervision (OTS) issued revisions to its examination procedures. The OTS has revised its examination procedures for closed-end loans as a result of recent Federal Reserve Board (FRB) revisions to Regulation Z, which implements the Truth in Lending Act (TILA).
Specifically, the revised procedures cover:
(1) Loan Originator Compensation: The prohibition on payments to loan originators, including mortgage brokers and loan officers employed by depository institutions, based on the terms of the transaction, other than the loan amount;
(2) Mortgage Disclosure Improvement Act: Required disclosure of payment examples if the loan's interest rate or payments can change and a statement that a consumer is not guaranteed to be able to refinance the transaction in the future;
(3) Appraiser Independence: Requirements for appraiser independence for consumer credit transactions secured by a consumer's principal dwelling, whether a closed-end loan or a home equity line of credit; and
(4) Helping Families Save Their Homes Act: Requirements that consumers receive notice when their mortgage loan has been sold or transferred. Examiners will be required to evaluate whether savings associations meet specific requirements.
Post Separator-2-LCG
LOAN ORIGINATOR COMPENSATION
Revised Examination Criteria
  • A loan originator, including mortgage brokers and mortgage loan officers employed by depository institutions, may not receive compensation that is based on the interest rate of the loan (i.e., a yield spread premium) or other loan terms. Loan originators can continue to receive compensation that is based on a percentage of loan amount.
  • A loan originator that receives compensation directly from the consumer may not receive compensation from the lender or another party.
  • A loan originator may not direct or "steer" a consumer to a mortgage loan that is not in the consumer's interest in order to increase the loan originator's compensation.
  • A loan originator can obtain a "safe harbor" for compliance with the anti-steering requirement by presenting the consumer with loan options that include: 1) the loan with the lowest interest rate; 2) the loan with the lowest interest rate without any risky features (such as prepayment penalties, negative amortization or a balloon payment in the first seven years); and 3) the loan with the lowest total dollar amount for origination points or fees and discount points.
Post Separator-2-LCG
MORTGAGE DISCLOSURE IMPROVEMENT ACT
Revised Examination Criteria
The Mortgage Disclosure Improvement Act (MDIA) of 2008 amended the TILA to require that borrowers are alerted to the risk of payment increases before they take out mortgages with variable rates or payments. This amendment requires that lenders' cost disclosures include a payment summary in the form of a table, stating the following:
  • The initial interest rate and the corresponding monthly payment;
  • For adjustable-rate or step-rate loans, the maximum interest rate and payment that can occur during the first five years and a "worst case" example showing the maximum rate and payment possible over the life of the loan; and,
  • The fact that consumers might not be able to avoid increased payments by refinancing their loans.
Post Separator-2-LCG
APPRAISER INDEPENDENCE 
Revised Examination Criteria
The Dodd-Frank Wall Street Reform and Consumer Protection Act amended the TILA to include several provisions that protect the integrity of the appraisal process when the consumer's home secures the loan, whether a closed-end loan or a home equity line of credit. 
Specifically, the appraisal independence provisions:
  • Prohibit coercion, bribery and other similar actions designed to cause appraisers to base the appraised value of properties on factors other than their independent judgment;
  • Prohibit appraisers and appraisal management companies from having a financial or other interest in the property or the credit transaction;
  • Prohibit a creditor from extending credit, if it knows, before consummation, of coercion or a conflict of interest;
  • Require that creditors or settlement service providers that have information about appraiser misconduct file reports with the appropriate state licensing authorities; and,
  • Require the payment of reasonable and customary compensation to appraisers who are not employees of the creditors or of the appraisal management company hired by the creditors.
Post Separator-2-LCG
HELPING FAMILIES SAVE THEIR HOMES ACT 
Revised Examination Criteria
The Helping Families Save Their Homes Act amended the TILA to require that consumers be notified of the sale or transfer of their mortgage loan. 
The purchaser or assignee that acquires the loan must provide the required disclosures no later than 30 days after the date on which it acquired the loan.
Post Separator-2-LCG
VISIT LIBRARY
Law Library Image
Office of Thrift Supervision (OTS)
Consumer Affairs Laws and Regulations:
Examination Handbook - Section 1305
May 2011

Thursday, March 24, 2011

Loan Originator Compensation: Good Faith Estimate (GFE)

On March 18, 2011, the Department of Housing and Urban Development (HUD) issued its RESPA Roundup, this issue being devoted to completing the Good Faith Estimate (GFE)  in order to disclose loan originator compensation pursuant to the new TILA Loan Originator Compensation rule (Rule). [75 F.R. 58509 (September 24, 2010)]
HUD's guidance addresses the following issues:
(1) Mortgage broker transactions where the broker is compensated indirectly from the lender by means other than an amount that is computed based on the interest rate, such as by a flat fee or an amount that is based on any other computation;
(2) No cost transactions where the credit for the interest rate chosen covers third party settlement charges;
(3) Using a credit/charge calculation prior to completing Block 2 on the GFE; and
(4) Payments by lenders to borrowers to correct tolerance violations in wholesale transactions.
I will simplify the technical aspects of this HUD issuance, in order to clarify how to complete the GFE.

Post Separator-2-LCG
(1) Mortgage Broker Transactions
(Flat Fee Compensation)
Block 2 instructions state: "[f]or a mortgage broker, the credit or charge for the specific interest rate chosen is the net payment to the mortgage broker from the lender (i.e., the sum of all payments to the mortgage broker from the lender, including payments based on the loan amount, a flat rate, or any other computation, and in a table funded transaction, the loan amount less the price paid for the loan by the lender)."
Illustration: Flat Fee Compensation
Example:
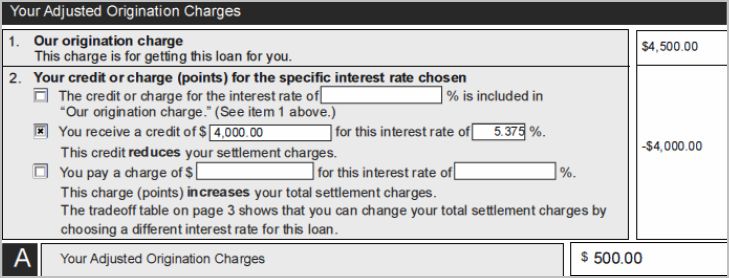
a) Flat Fee to Mortgage Broker is $4,000 (to be paid by the lender).
b) The lender charges $500 for processing and administrative fees. 
GFE: Block 1 reflects a charge of $4,500. (Block 2 has a credit of $4,000, adjusted origination charge of $500 in Block A.)

GFE-1-LOCompensation
Post Separator-2-LCG
(2) No Cost Transactions
(Interest Rate Covers Originator

or Third Party Settlement Charges)
Overview:
Only Originator Fees: Line A would show a zero (0) charge as the adjusted origination charge. 
Originator Fees and Third Party Charges: All third party fees must still be itemized and listed in Block 3 through Block 11 on the GFE. 
NOTE (1): Block 1 includes lender and mortgage broker compensation as well as all other charges that the lender and mortgage broker will receive. Thus, Block 1 provides total compensation to lender and mortgage broker.
NOTE (2): Block 2 is used for the credit or charge for the interest rate chosen. 
(A) If "no cost" refers to only the lender and mortgage broker's fees, Block 2 offsets Block 1 resulting in $0 on Line A.
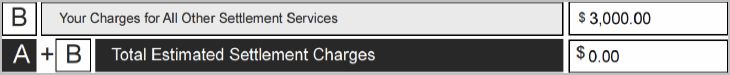
(B) If "no cost" refers to both Block 1 and the third party settlement charges (itemized in Blocks 3-11), the credit in Block 2 covers Block 1 and Blocks 3 through 11, resulting in $0 for the sum of Lines A and B.
Example
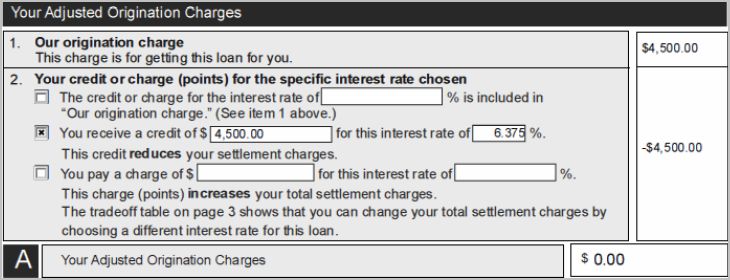
No cost loan covering only lender and mortgage broker charges (i.e., not third party settlement charges). 
In the following GFE, the total compensation for the lender and mortgage broker is $4,500, as reflected in Block 1. Borrower is locked in an interest rate of 6.375% such that the credit for the interest rate chosen results in a credit of $4,500. Thus, Block A results in $0.

GFE-2-LOCompensation

Example
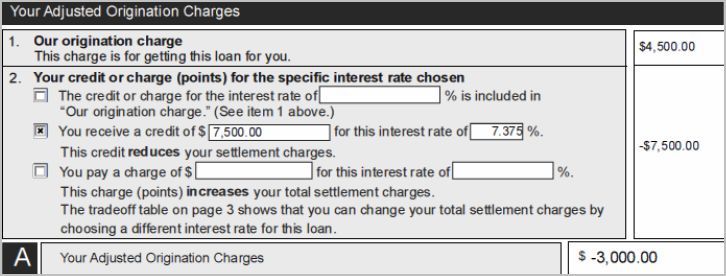
No cost loan covering lender, mortgage broker and third party settlement charges.
In the following GFE, the total compensation for both the lender and mortgage broker is $4,500, as reflected in Block 1. The borrower has locked in an interest rate of 7.375% such that the credit for the interest rate chosen results in a credit of $7,500. Block A results in a credit of $3,000 to offset the total of all third party charges in Block 3 through Block 11.

GFE-3-LOCompensationGFE-3A-LOCompensation

Post Separator-2-LCG
(3) Using a Charge or Credit Calculation
Prior to Completing Block 2 of the GFE 

Overview:
RESPA provides: "[w]hen the net payment to the mortgage broker from the lender is positive, there is a credit to the borrower and it is entered as a negative amount in Block 2 of the GFE. When the net payment to the mortgage broker from the lender is negative, there is a charge to the borrower and it is entered as a positive amount in Block 2 of the GFE." 
NOTE: the Rule prohibits a loan originator (as defined by the FRB) from receiving compensation directly from the consumer when it has received compensation from any person other than the consumer in connection with the transaction.
Example: Charge in Block 2
a) Principal balance is $250,000.
b) Lender charges $1,000 for processing and administrative fees.
c) Broker's compensation is $2,000, fully paid by the lender.
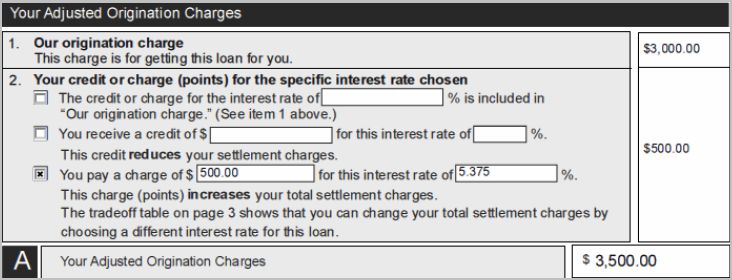
In the following GFE, the total origination charge in Block 1 is $3,000. The interest rate chosen a $2,000 credit. Pricing adjustments result in a $2,500 charge. The resulting $500 charge is placed in Block 2 and box three would be checked. The sum of Block 1 and Block 2 results in an adjusted origination charge in Line A of $3,500.

GFE-4-LOCompensation
Example: Credit in Block 2
a) Principal balance of $250,000.
b) Lender charges $1,000 for an origination fee.
c) Broker receives $2,000 in indirect compensation from the lender.

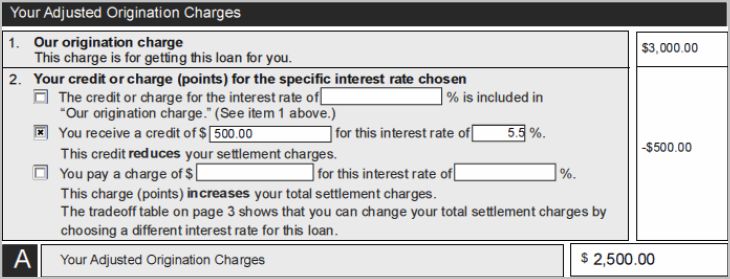
In the following GFE, the total origination charge in Block 1 is $3,000. The interest rate chosen has a $2,000 credit. Pricing adjustments result in a $1,500 charge. The resulting $500 credit is placed in Block 2 and box two would be checked. The sum of Block 1 and Block 2 results in an adjusted origination charge in Line A of $2,500.

GFE-5-LOCompensation
Post Separator-2-LCG
(4) Payments by Lenders to Borrowers for
Tolerance Violations in Wholesale Transactions
HUD restates the RESPA statute by emphasizing that regulations impose tolerance levels on charges disclosed on the GFE. Where actual charges to the borrower exceed these thresholds, mortgage brokers and lenders may cure to avoid a tolerance violation.
Advice given by HUD: timely and effective communication among the lender, its loan officers, and mortgage brokers to establish policies and procedures to ensure accurate calculation of compensation and credits in compliance with RESPA, as well as under the FRB compensation rule and any other applicable federal or state statute.
In other words, in HUD's view tolerance violations remain the burden to cure, though HUD provides no further guidance.

Post Separator-2-LCG
Some Observations
Changed Circumstances: The FRB's compensation rule will go into effect on April 1, 2011 and absent other factors cannot be considered a basis for a changed circumstance to revise the GFE pursuant to 24 C.F.R. §3500.7(f).
Volume Based Compensation: If a lender is basing its compensation to mortgage brokers on loan volume, as described in the new FRB compensation rule, it is nevertheless necessary to comply with RESPA Section 8 (12 U.S.C. 2607), which prohibits the payment of things of value or kickbacks in exchange for the referral of business to settlement service providers, including creditors.
Company Name Disclosed in Section F of the HUD-1: The name of the company originating the loan should be placed in Section F of the HUD-1. The name of any individual loan officer or mortgage broker is not disclosed.

Post Separator-2-LCG
Visit Library
Law Library Image
Compliance Guidance for RESPA's Good Faith Estimate:
FRB's MLO Compensation Rules
HUD - RESPA Roundup,
March 18, 2011

Tuesday, December 14, 2010

Yield Spread Premium: Excluded from HOEPA

By Jonathan Foxx

Jonathan Foxx, former Chief Compliance Officer of two publicly traded financial institutions, is the President and Managing Director of Lenders Compliance Group, the first full-service, mortgage risk management firm in the country.

Line-Webpage

As you may know, I have lectured extensively and written many articles relating to the Yield Spread Premium (YSP).

And I will continue to track issues involving the YSP.

Here are some of my recent articles:

  • Service Release Premium vs Yield Spread Premium: Match or Mismatch?
  • Saving the Yield Spread Premium
  • Yield Spread Premiums: Compensation or Kickback?

During the course of this multi-year, ongoing review, I have been following litigation that affects the YSP.

Just such litigation that has national implications is the recent decision on November 30, 2010 by the Louisiana Supreme Court, which held that the YSP is excludable from the Home Ownership and Equity Protection Act (HOEPA) calculation.

On one side was The Bank of New York (Bank) and on the other side was Kathleen Johnson Parnell (Parnell) along with amici curiae such as the National Consumer Law Center, Center for Responsible Lending, and the Southeastern Louisiana Legal Services.

At risk was the interpretation of the FRB's Official Staff Commentary to the Truth in Lending Act as well as a public attempt to portray the lender in the worse possible light.

I thought you might find this recent decision of interest.

Best wishes,
Jonathan

Line-Webpage

Overview

The Louisiana Supreme Court held that a YSP paid by a lender to a mortgage broker is not part of the "total points and fees payable by the consumer at or before closing," within the meaning of 15 U.S.C. § 1602(aa)(1)(B) of HOEPA.

To quote the ruling itself: "Because the YSP in this case was paid by the lender not the borrower/consumer, the YSP is not included in the calculation for determining the applicability of HOEPA."

The Court used the Truth In Lending Act as its source and relied on a provision in the Federal Reserve Board's Official Staff Commentary of Regulation Z to find that mortgage broker fees which are not paid by the consumer are not included in the HOEPA "points and fees" calculation.

Indeed, the Court cited the Dodd-Frank Wall Street Reform and Consumer Protection Act (2010) in its amending of 15 U.S.C. § 1602(aa)(1) replacing "points and fees payable by the consumer at or before closing" with "points and fees payable in connection with the transaction."

The Court decided that "the YSP in this case was not payable [by the consumer] at or before closing as required by the applicable version of 15 U.S.C. § 1602(aa)(1)(B)."

Line-Webpage

Some Case Facts

Fact Pattern
1) 2001: Kathleen Johnson Parnell (Parnell) executed an adjustable rate promissory note secured by her home.
2) Loan was originated through a mortgage broker.
3) HUD-1 Settlement Statement stated that the lender paid the mortgage broker a YSP in the amount of $1,264, which was paid outside closing.
4) 2003: Parnell attempted to rescind the security interest under the Truth In Lending Act claiming:
4-A) that her loan was governed by HOEPA (because points and fees exceeded 8% of the total loan amount), and
4-B) that she had not been given the requisite disclosures.

Dispute
1) Parnell's rescission demand was denied because the threshold requirement of HOEPA was not met, being the total amount of points and fees of only 6.7%.
2) The difference between these calculations rested on the inclusion of the YSP.

Litigation
1) Parnell defaulted on her note.
2) The Bank filed a petition for executory process seeking to seize and sell her home.
3) Parnell filed a petition to suspend the seizure and sale of her home, alleging, among other things, a violation of HOEPA for failing to provide statutorily-required disclosures.
4) The Bank filed a motion for summary judgment, seeking the dismissal of all claims asserted by Parnell primarily on the basis that Parnell's loan was not subject to HOEPA because a YSP paid by a lender is not included in the points and fees calculation.
5) Parnell opposed the Bank's motion arguing that the YSP was ultimately paid by her over the life of the loan and that "all compensation paid to mortgage brokers" constitute "points and fees" under HOEPA.
6) The trial court granted the Bank's motion for summary judgment.
7) Louisiana Court of Appeal for the Fifth Circuit reversed on appeal.
8) Louisiana Supreme Court decided that those portions of the appellate court decision that reversed the trial court's granting of summary judgment in favor of the Bank as to Parnell's HOEPA and wrongful seizure claims are reversed. And, with respect to these two claims, the judgment of the trial court was reinstated.

Line-Webpage

Visit Library for Issuance

Law Library Image
The Bank of New York, Acting Solely in Its Capacity As Trustee for
EQCC Trust 2001-2 v. Kathleen Johnson Parnell

No. 2010-C-0435 (LA: 11/30/2010)

Line-Webpage

LENDERS COMPLIANCE GROUP is the first full-service, mortgage risk management firm in the country, specializing exclusively in mortgage compliance and offering a full suite of hands-on and automated services in residential mortgage banking.

Thursday, September 30, 2010

A PROCLAMATION: COMPENSABLE SERVICES FEE

COMMENTARY by JONATHAN FOXX

Jonathan Foxx, former Chief Compliance Officer of two publicly traded financial institutions, is the President and Managing Director of Lenders Compliance Group.

Lenders Compliance Group is the first full-service, mortgage risk management firm in the country and pioneers in outsourcing solutions in regulatory compliance.

Published in the September 2010 Edition of National Mortgage Professional Magazine.

____________________________________

I have published an article that I think you'll want to read. The article provides the rationale for introducing a new term, which I have named the Compensable Services Fee, to replace the term Yield Spread Premium. The article is written in the form of a Proclamation.

As you may know, I have lectured on and written rather extensively about the Yield Spread Premium, for example:

  • A New Era of Mortgage Reform - Part II: Legislation - Reactive or Proactive (September 2010 Edition)
  • Landmark Financial Legislation: New Rules for Mortgage Originators -Part I: Reformation and Regulations (August 2010 Edition)
  • New RESPA Reform Rule - Overview (January 2010 Edition)
  • Service Release Premium vs. Yield Spread Premium: Match or Mismatch? (August 2009 Edition)
  • Saving the Yield Spread Premium (July 2009 Edition)
  • Yield Spread Premiums: Compensation or Kickback? (June 2009 Edition)

ALL THESE ARTICLES CAN BE FOUND HERE and were published in National Mortgage Professional Magazine, the mortgage industry's leading national magazine.

Now that the Yield Spread Premium (YSP) has gone the way of nature, and a credit has taken its place, perhaps it's time to make sure that the public understands that the credit, in whole or in part, provides payment for goods and services that the mortgage broker has actually rendered.

Or, to be blunt about it: notwithstanding politics and negative publicity, there is no RESPA Section 8 "kickback" when a mortgage broker actually furnishes and provides those goods and services and the compensation is reasonably related to the value of the goods and services actually furnished and provided!

The new Good Faith Estimate, which became effective January 1, 2010, reflects the change from YSP to credit.

But does the mortgage loan applicant actually know what the credit actually pays?

I am pleased to share this article with you. Special thanks to National Mortgage Professional Magazine for the opportunity to publish this Proclamation.

Lenders Compliance Group provides expert guidance in all areas of mortgage compliance.

If you are not yet a client, shouldn't you become one?

We are the first full-service, mortgage risk management firm in the country, and pioneers in outsourcing solutions. It would be a pleasure to support all your regulatory compliance needs.

If you have questions about this matter or would like assistance with mortgage compliance, please contact me at any time.

____________________________________

Excerpt

Action Button Image 1Because the Yield Spread Premium is effectively gone from disclosure and the credit is to be used to partially or fully pay for the mortgage broker's services, a new term should be used to assure the public of the unique purpose of that credit, with respect to the goods and services actually provided by the mortgage broker.

Consequently, I would like to offer a new term to the industry to help assure the public's positive perception of the critical role played by mortgage brokers.

Behold my PROCLAMATION of a new term:

Compensable Services Fee!

A PROCLAMATION
CONCERNING
THE NEW TERM
"COMPENSABLE SERVICES FEE"
TO DESCRIBE COMPENSATION
EARNED BY MORTGAGE BROKERS
IN
RESIDENTIAL MORTGAGE LOAN TRANSACTIONS

Please read the PROCLAMATION and pass it around, so that mortgage brokers may explain to loan applicants, for educational and promotional purposes, that the compensation for their services are legitimately earned, legal, critical, and necessary to residential mortgage loan originations.

Download Origination Article (1.75) ___________________________________

LENDERS COMPLIANCE GROUP is the first full-service, mortgage risk management firm in the country, specializing exclusively in mortgage compliance and offering a full suite of hands-on and automated services in residential mortgage banking.

Tuesday, August 17, 2010

Mortgage Originator Compensation and the Dodd-Frank Act

We now enter the era when the Dodd-Frank Act has become the law of the land. Today's brief review (provided below) is at the advent of this period and introduces some of the many changes resulting from this landmark legislation.

But first a comment.

Consolidation of regulatory authorities will be considerable!

There will be transfer and consolidation of enforcement authorities into the Consumer Financial Protection Bureau (Bureau) over the consumer financial protection functions currently performed by the Federal Reserve's Board of Governors, the Office of the Comptroller of the Currency (OCC), the Office of Thrift Supervision (OTS), the Federal Deposit Insurance Corporation (FDIC), the National Credit Union Administration (NCUA) and the Federal Trade Commission (FTC) - including exclusive authority over all related research, rulemaking, guidance, supervision, examination and enforcement activities.

At least sixteen (16) existing consumer protection laws will be included in the transfer, giving new exclusive rulemaking and examination authority to the Bureau.

I have published articles extensively on this subject; indeed, forthcoming this month, I will publish a 3-part series in the National Mortgage Professional Magazine on the financial reform legislation and its impact on the mortgage industry.

If you want to read more, go PDF 12x12here, PDF 12x12here, here, and here.

For the next few years, we will be seeing numerous announcements implementing the changes required by the Dodd-Frank Act. These issuances will come from various agencies as well as the new Bureau and will affect revisions to existing regulations, enumerated laws, Bureau mandates, and many other implementation requirements.

It is essential that you review and continually monitor for these changes, because there will indeed be many and, in various instances, the statutory requirements are complex, extensive, and interlock or interact with other laws - and violations can be enormously costly.

Because of the many regulatory compliance areas that are affected, we urge you to approach the required compliance proactively, seeking guidance now from a competent residential mortgage compliance professional.

Overview

On August 16, 2010, the Federal Reserve Board announced final rules to protect mortgage borrowers from unfair, abusive, or deceptive lending practices that can arise from loan originator compensation practices. The new rules apply to mortgage brokers and the companies that employ them, as well as mortgage loan officers employed by depository institutions and other lenders. The Board is publishing these final rules, amending Regulation Z, which implements the Truth in Lending Act (TILA) and Home Ownership and Equity Protection Act (HOEPA).

At this time, lenders may pay loan originators more compensation if the borrower accepts an interest rate higher than the rate required by the lender (commonly referred to as a "yield spread premium"). Under the final rule, however, a loan originator may not receive compensation that is based on the interest rate or other loan terms. The ostensible purpose of this regulation is to prevent loan originators from increasing their own compensation by raising the consumers' loan costs (i.e., by increasing the interest rate or points).

However, loan originators can continue to receive compensation that is based on a percentage of the loan amount.

There is also a prohibition that prevents a loan originator that receives compensation directly from the consumer from also receiving compensation from the lender or another party. This new rule requires that consumers who agree to pay the originator directly will not also pay the originator indirectly through a higher interest rate, thereby paying more in total compensation than they realize.

The final rule prohibits loan originators from directing or "steering" a consumer to accept a mortgage loan that is not in the consumer's interest in order to increase the originator's compensation.

The final rules apply to closed-end transactions secured by a dwelling where the creditor receives a loan application on or after April 1, 2011.

Effective Compliance Date: April 1, 2011.

If you have any questions about this matter or would like assistance with mortgage compliance, please contact Jonathan Foxx.

Highlights

  • Prohibits payments to the loan originator that are based on the loan's interest rate or other terms. Compensation that is based on a fixed percentage of the loan amount is permitted.
  • Prohibits a mortgage broker or loan officer from receiving payments directly from a consumer while also receiving compensation from the creditor or another person.
  • Prohibits a mortgage broker or loan officer from "steering" a consumer to a lender offering less favorable terms in order to increase the broker's or loan officer's compensation.
  • Provides a safe harbor to facilitate compliance with the anti-steering rule.

The safe harbor is met if:

1. The consumer is presented with loan offers for each type of transaction in which the consumer expresses an interest (that is, a fixed rate loan, adjustable rate loan, or a reverse mortgage); and

2. The loan options presented to the consumer include the following:

  • (A) the lowest interest rate for which the consumer qualifies;
  • (B) the lowest points and origination fees, and
  • (C) the lowest rate for which the consumer qualifies for a loan with no risky features, such as a prepayment penalty, negative amortization, or a balloon payment in the first seven years.

Visit Library for Issuances

Law Library Image

Truth in Lending, 12 CFR Part 226, Final rule and Official Staff Commentary, FRB (8/16/10)

Highlights of Final Rules on Loan Originator Compensation and Steering, FRB (8/16/10)

Lenders Compliance Group is the first full-service, mortgage risk management firm in the country, specializing exclusively in mortgage compliance and offering a full suite of hands-on and automated services in residential mortgage banking.

Monday, August 16, 2010

Good Faith Estimate: Top 10 Broker Mistakes

Since the introduction of the effective implementation date of the new Good Faith Estimate (GFE) on January 1, 2010, we have been working closely with our clients to assure proper disclosure compliance. During this time, we have documented literally hundreds of issues that have required resolution and guidance pertaining not only to the GFE but also the new HUD-1 Settlement Statement (HUD-1).

Even now, these many months into the use of the new GFE, we receive numerous requests from clients seeking a better understanding of this form's nuances and requirements.

Regarding proper implementation of the GFE and HUD-1, we have compiled a database of resolutions and guidelines for regulatory compliance, and will soon make it available to our clients in the first release of our online client website.

However, there are still gaps and we look to the Department of Housing and Urban Development (HUD) for further written clarifications.
There have been eight (8) updates to the New RESPA Rule FAQs (RESPA FAQs) since HUD issued the Final Rule on November 17, 2008: six were issued in 2009, and two were issued in 2010 - with the second (and most recent) issued on April 2, 2010. Although HUD issued a RESPA Roundup in July, that document provided virtually no GFE guidance.

Given that the last RESPA FAQs update was in early April, another update is long overdue. HUD should update the RESPA FAQs soon.

We thought we'd share with you some mistakes made by mortgage brokers and the positions taken by our wholesale lending clients in response to those errors. Obviously, our retail mortgage banker clients have different issues and disclosure concerns. Nevertheless, wholesale lending has certain issues quite unique to the origination and loan flow processes.

If you have any questions about this matter or would like assistance with mortgage compliance, please contact Jonathan Foxx.

Highlights

Top 10 GFE Mistakes Made By Brokers

1. Broker submits a 2009 GFE. The 2010 HUD-approved GFE is the only version acceptable to the lender. Obviously, this mistake was happening during the early transition period, but the percentage of occurrences was inordinately high at the time.

2. Broker submits a 2010 GFE without a complete Service Provider List. All GFEs must include a Service Provider List and must clearly indicate all services that the broker has chosen for the borrower if the broker is selecting the provider. If the borrower chooses from the service provider(s) or if the broker chooses the service provider(s) the 10% tolerance must be adhered to.

3. Broker includes the YSP in Line #1, but leaves Line #2 completely blank. Line 2 should always be the Gross YSP. The adjustment for what the broker wants to make as income and what the broker would like to credit the borrower is adjusted in Line 1.

Here's an example taken from our files:

Scenario-1

4. Broker includes the YSP in Line #2, but fails to include it in Line #1. The adjustment for what the broker wants to make as income and what the broker would like to credit the borrower is adjusted in Line 1.

Here's an example taken from our files:

Scenario-2

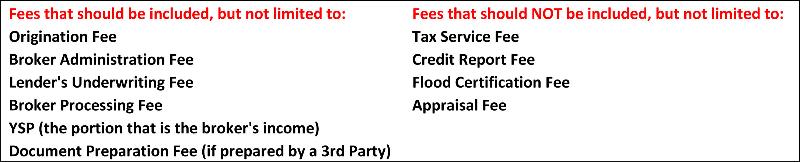
5. Broker does not disclose the lender's underwriting fee in Line #1. The lender's underwriting fee should be included in Line #1.

6. Broker leaves Line #1 completely blank or is calculated incorrectly. Line #1 should include all income fees for the broker and lender.

Here's an outline taken from our files:

Chart-GFE-Outline-3

7. Broker does not include 3rd party fees in Line #3. Third party fees, including lender's fees [i.e., Tax Service Fee, Flood Certification Fee, Appraisal Fee (even if it is paid outside of closing), Credit Report Fee, FHA Upfront Mortgage Insurance Premium (MIP) Fee VA Funding Fee, and so forth], should be included in Line #3.

8. Broker does not disclose any and all seller paid items. All fees should be included on the GFE even if the seller is paying closing costs.

9. Broker does not include the transfer tax fees on the GFE in states where transfer tax is a requirement. The transfer tax fees must be disclosed in states where required. If state or local law is unclear or does not specifically attribute transfer tax to a seller or the borrower, the amount to be disclosed by the broker is governed by common practice or experience in the locality. Because not disclosing this fee is in the zero tolerance box, our wholesale lenders charge the broker if not disclosed upfront.

10. Broker does not include all income fees in Box 1 including the lender's underwriting fee. All broker income fees must be included in Box 1 along with the lender's underwriting fee. No additional fees can be added after the initial GFE.

Visit Library for Issuances

Law Library Image

New Good Faith Estimate and HUD-1 Settlement Statement
RESPA - Final Rule and New RESPA Rule FAQs

Lenders Compliance Group is the first full-service, mortgage risk management firm in the country, specializing exclusively in mortgage compliance and offering a full suite of hands-on and automated services in residential mortgage banking.