CREATORS OF THE COMPLIANCE TUNE-UP®

AARMR | ABA | ACAMS | ALTA | ARMCP | IAPP | IIA | MBA | MERS® | MISMO | NAMB

Showing posts with label National Mortgage Licensing System. Show all posts

Friday, January 14, 2011

NMLS: MLO Registration to Commence

In its first Financial Institution Letter of the year, the FDIC issued on January 4, 2011 its issuance FIL-1-2011 in which the Office of the Comptroller of the Currency, the Board of Governors of the Federal Reserve System,, the Federal Deposit Insurance Corporation, the Office of Thrift Supervision, the Farm Credit Administration, and the National Credit Union Administration, (collectively, Agencies) announced that they expect the system for federal registration of residential mortgage loan originators (MLOs) to begin operation on or around January 31, 2011.

The Agencies' rules implementing the SAFE Act require MLOs to register with the Nationwide Mortgage Licensing System and Registry (Registry) within 180 days of the date the Registry begins accepting federal registrations. The Agencies will confirm the opening date for federal registration closer to the actual date and will publish notice of that date in the Federal Register.

On July 28, 2010, the Agencies announced the Federal Register publication of rules implementing the SAFE Act through this joint press release.

In any event, the federal bank and thrift regulatory agencies have said that they expect to be ready to accept residential mortgage loan originator registrations by about January 31, 2011.

Under the Secure and Fair Enforcement for Mortgage Licensing Act of 2008 (S.A.F.E. Act), loan originators must register with the Nationwide Mortgage Licensing System and Registry within 180 days of the date the Registry announces it can accept registrations. A precise date will be published in the Federal Register when it is determined, the agencies said.

A loan originator that does not register within the 180-day period will be prohibited from originating residential mortgage loans until it has completed its registration. There will be an exception for those who originated no more than five loans during the previous 12 months.

Rules adopted jointly by the agencies establish the registration requirements for loan originators employed by agency-regulated institutions and set the requirements for these institutions, which include the adoption of policies and procedures to ensure compliance with the S.A.F.E. Act and final rules.

The rules also require that each loan originator obtain a unique identifier through the Registry that will remain with that loan originator, regardless of changes in employment. This is intended to give consumers access to employment and other background information about loan originators. Registered mortgage loan originators and agency-regulated institutions will be required to provide these unique identifiers to consumers.

Compliance Effective: On or around January 31, 2011

Separator-Glow

OUTLINE OF MLO REGISTRATION TIMEFRAME

Separator-Glow

  • The press release states that advance notice would be provided for the date the Registry would begin accepting federal registrations: the Agencies currently expect federal registration to begin on January 31, 2011.
  • MLOs employed by Agency-regulated institutions will have 180 days from the date on which the Registry begins accepting federal registrations to complete initial registration. At present, the Agencies expect the initial registration period to expire on July 29, 2011.
  • After the initial registration period expires, MLOs will be prohibited from originating residential mortgage loans until they successfully complete the federal registration process.
  • The Agencies' rules provide a de minimis exception whereby MLOs that originated 5 or fewer mortgage loans during the previous 12 months are not required to complete the federal registration process.
  • The Agencies will confirm the actual registration start date before the initial registration period begins and publish an announcement in the Federal Register.

Visit Library for Issuance

Law Library Image

SAFE Act - Update: Registration of Residential Mortgage Loan Originators, FIL-1-2011
January 4, 2011

Post Separator-2-LCG

Monday, January 10, 2011

FHA: Connects to the NMLSR

On January 5, 2011, HUD-FHA issued Mortgagee Letter 2011-04, which notifies mortgagees that HUD will begin collecting the unique identifiers assigned by the Nationwide Mortgage Licensing System and Registry (NMLS) to individuals and entities participating in the origination of loans submitted for insurance by the FHA.

FHA-approved mortgagees and their employees must comply with the NMLS registration requirements of the states and entities with jurisdiction over their activities, and must register in accordance with the guidelines set forth by the NMLS.

Additionally, Sponsoring Third Party Originators are now required to ensure that their Sponsored Third Party Originators obtain and maintain an NMLS unique identifier (NMLS ID), as is required by the states and entities with jurisdiction over their activities and in accordance with the registration guidelines set forth by the NMLS.

Please also note that under the Helping Families Save Their Homes Act of 2009 (Pub.L. 111-22), the failure of an FHA-approved lender to comply with requirements of the Safe Act (12 U.S.C. 5101-5116) and applicable state law is cause for withdrawal of FHA lender approval or loss of authorization to participate in FHA lending programs.

HUD expects mortgagees to comply with applicable federal and state requirements governing NMLS licensing and registration. For more information on your state's NMLS requirements and implementation plans, you can visit the NMLS Resource Center.

HUD will capture NMLS IDs at a number of points in the lender approval and loan origination processes, which we have indicated below.

Read Below for Compliance Deadlines.

Line-Webpage

DATA CAPTURE OF NMLS IDENTIFIERS

Line-Webpage

APPLICATION FOR OR RENEWAL OF FHA LENDER APPROVAL

HUD will collect the NMLS company ID:

  • From lenders seeking approval to participate in FHA programs via a new field in the "Application for Federal Housing Administration Lender Approval" (Form HUD-92001-A). The revised Form HUD-92001-A is expected to be released soon and available on HUD's document website.
  • From lenders seeking to renew their FHA lender approval via the completion of a new field in the renewal screens in FHA Connection. Changes to the renewal screens in FHA Connection were released on October 4, 2010.

Completion of these new fields will become mandatory upon their release for those institutions that possess an NMLS company ID.

Line-Webpage

SPONSORING THIRD PARTY ORIGINATORS

HUD will collect the NMLS company ID of Sponsored Third Party Originators:

From Sponsoring Third Party Originators, by their completing the Sponsored Originator Maintenance screen in FHA Connection.

Line-Webpage

LOAN PROCESSING AND UNDERWRITING

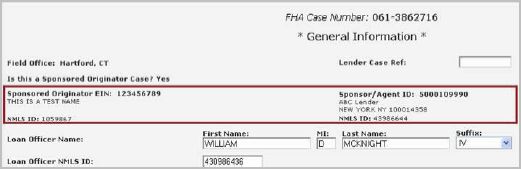
Mortgagees will be required to complete the following new fields on the FHA Connection case number assignment screen, as appropriate:

1) Loan Officer: the NMLS ID of the loan officer who took the application from the applicant.
We expect this information to be used, among other things, to observe and enforce compliance with loan officer licensing requirements. Disclosure compliance regarding this data will likely be included in HUD's quality assurance examinations.

2) Sponsored Third Party Originator loans: the Sponsored Third Party Originator's company name and Taxpayer Identification Number (if applicable).
HUD will use the information to provide the Sponsoring Third Party Originators with Neighborhood Watch performance data for their Sponsored Third Party Originators. We expect the information to be used by HUD to assist in ensuring that participants in FHA loan transactions comply with the eligibility requirements governing participation in FHA programs.

Compliance Dates

Until March 31, 2011: entry of the name and NMLS ID of a loan officer is optional.

On and after April 1, 2011: the information must be entered in accordance with the following guidelines:

-The loan officer's first and last name are required, and

-If registered in NMLS, the loan officer's NMLS ID is required.

Here's a screen shot:
Case Number-NMLS
FHA Case Number Screen - General Information

Line-Webpage

HUD/VA ADDENDUM TO UNIFORM RESIDENTIAL LOAN APPLICATION
(HUD 92900-A)

Changes have been made to form HUD 92900-A, "HUD/VA Addendum to Uniform Residential Loan Application," to capture the company name, Taxpayer Identification Number and NMLS ID (if applicable) of a Sponsored Third Party Originator company.

Sponsoring Third Party Originator mortgagees may obtain the revised form at HUD's document website.

HUD 92900-A (9/2010): must be used for all loan applications taken by a Sponsored Third Party Originator.

HUD 92900-A (5/2008): may be used for loan originations not involving a sponsored originator until January 1, 2011.

Line-Webpage

Visit Library for Issuance

Law Library Image
FHA Capture of Nationwide Mortgage Licensing System and Registry (NMLS) Information
Mortgagee Letter 2011-04
January 5, 2011

Post Separator-2-LCG

LENDERS COMPLIANCE GROUP is the first full-service, mortgage risk management firm in the country, specializing exclusively in mortgage compliance and offering a full suite of hands-on and automated services in residential mortgage banking.

Thursday, July 29, 2010

SAFE Act: Final Rules for Mortgage Loan Originators

MORTGAGE COMPLIANCE

On July 28, 2010, the federal agencies issued final rules requiring residential mortgage loan originators (MLO) who are employees of national and state banks, savings associations, Farm Credit System institutions, credit unions, and certain of their subsidiaries (agency-regulated institutions) to meet the registration requirements of the Secure and Fair Enforcement for Mortgage Licensing Act of 2008 (SAFE Act).

An MLO as an individual who: (i) takes a residential mortgage loan application; and, (ii) offers or negotiates terms of a residential mortgage loan for compensation or gain.

Excluded from the registration requirement are individuals engaged in modifications and assumptions, since those transactions do not result in the extinguishing of an existing loan and the replacement with a new loan.

The SAFE Act does not require employees of mortgage loan servicers to be licensed as MLOs; indeed, the Dodd-Frank Wall Street Reform and Consumer Protection Act excludes servicers, providing in its separate definition of "mortgage originator" under the Truth in Lending Act that those persons, among others, do not include servicers and their employees, agents, or contractors.

The newly created Consumer Financial Protection Bureau (CFPB) will be assuming HUD's role of determining whether states have met the SAFE Act's minimum requirements, and undoubtedly the CFPB will clarify whether the SAFE Act requires employees of mortgage loan servicers to be licensed as originators.

As part of this registration process, MLOs must furnish to the Nationwide Mortgage Licensing System and Registry (Registry) information and fingerprints for background checks. The SAFE Act generally prohibits employees of agency-regulated institutions from originating residential mortgage loans unless they register with the registry.

The agencies' final rules establish the registration requirements for MLOs employed by agency-regulated institutions and requirements for these institutions, including the adoption of policies and procedures to ensure compliance with the SAFE Act and the final rules.

Importantly, the agencies anticipate that the Registry could begin accepting federal registrations as early as January 28, 2011.

Employees of agency-regulated institutions must not register until the agencies instruct them to do so. The agencies will provide an advance announcement of the date when the registry will begin accepting federal registrations, beginning on the date the Agencies provide in a public notice that the Registry is accepting initial registrations, and agency-regulated institutions and their applicable employees will have 180 days from that date to comply with the initial registration requirements.

Final Rule Effective: October 1, 2010.

If you have any questions about this matter or would like assistance with mortgage compliance, please contact Jonathan Foxx, Managing Director.

Highlights

Registration of Mortgage Loan Originators (MLO)

  • Registration requirement. Each employee of a national bank who acts as a mortgage loan originator must register with the Registry, obtain a unique identifier, and maintain this registration in accordance with the requirements of the final rule.
  • Implementation period for initial registration. An employee of a national bank who is a mortgage loan originator must complete an initial registration with the Registry pursuant to the final rule within 180 days from the date that the OCC provides in a public notice that the Registry is accepting Registrations.
  • Employees previously registered or licensed through the Registry. In general. If an employee of a national bank was registered or licensed through, and obtained a unique identifier from, the Registry and has maintained this registration or license before the employee becomes subject to the final rule at this bank, then the registration requirements of the SAFE Act and the final are deemed to be met, provided that certain conditions are met.

Policies and Procedures

  • A national bank that employs one or more MLOs must adopt and follow written policies and procedures designed to assure compliance with the final rule.
  • Policies and procedures must be appropriate to the nature, size, complexity, and scope of the mortgage lending activities of the bank, and apply only to those employees acting within the scope of their employment at the bank.

Use of Unique Identifier

  • A national bank shall make the unique identifier(s) of its registered mortgage loan originator(s) available to consumers in a manner and method practicable to the institution.
  • A registered mortgage loan originator shall provide his or her unique identifier to a consumer:

1. Upon request;

2. Before acting as a mortgage loan originator; and

3. Through the originator's initial written communication with a consumer, if any, whether on paper or electronically.

Visit Library for Issuance

Law Library Image

Registration of Mortgage Loan Originators - Final Rule
Federal Register, Vol. 75, No. 144, 44656-44708, (7/28/10)

Lenders Compliance Group is the first full-service, mortgage risk management firm in the country, specializing exclusively in mortgage compliance and offering a full suite of hands-on and automated services in residential mortgage banking.

Thursday, July 8, 2010

Mortgage Call Reports – Coming Soon!

Overview

On March 15, 2010, on behalf of the state regulatory agencies participating in the Nationwide Mortgage Licensing System and Registry (NMLSR), the State Regulatory Registry invited public comments on the proposed implementation of a NMLS Mortgage Call Report (Report), which is intended to replace and standardize annual reports required by state regulators, provide necessary information to supervise state mortgage licensees, and fulfill the requirements of the Secure and Fair Enforcement for Mortgage Licensing Act of 2008 (SAFE Act).

The comment period closed on Friday, May 14, 2010. Notwithstanding that deadline, the NMLSR was accepting comments in response to the proposal as late as May 28, 2010.

Since June 2009, a working group of state regulators have been developing the Report and accompanying policies. When implemented, the Report will institute significant obligations for large and small mortgage company licensees, requiring them to report a far more extensive set of mortgage loan activity and financial information, in a more detailed manner, and more frequently, than any state has ever required such mortgage activity and financial information to be reported by a licensee.

The legal authority is claimed under the SAFE Act itself. State regulators use the SAFE Act for their authority to impose on licensees the information gathering requirements of a Mortgage Call Report. That is, the SAFE Act is intended to provide for the (1) registration of the loan originator employees of institutions regulated by the federal banking agencies, and (2) licensing of loan originators who are employees of state-licensed mortgage companies.

Section 1505 of the SAFE Act (12 U.S.C. 5104) sets forth the requirements that must be met for an individual to be a state-licensed loan originator. Subsection (e) of Section 1505 of the SAFE Act (12 U.S.C. 5104(e)) states:

"MORTGAGE CALL REPORTS -- Each mortgage licensee shall submit to the National Mortgage Licensing System and Registry reports of condition, which shall be in such form and shall contain such information as the Nationwide Mortgage Licensing System and Registry may require."

This provision is worded broadly. The SAFE Act does not otherwise address the Mortgage Call Reports. State regulators have concluded that because the term mortgage licensee,as used only in this section of the SAFE Act, is undefined, and appears to be distinct from the term loan originator (which is actually defined in12 USCA 5102), and because the phrase "reports of condition" is a phrase drawn from banking supervision of federally insured depository institutions, the Mortgage Call Report must be a statement of condition on the company that employs licensed mortgage loan originators and its operations (including financial statements and production activity volumes reported per state).

Many industry representatives believe that since the Mortgage Call Report provision requires each mortgage licensee to submit reports of condition to the NMLSR, and as the NMLSR is limited licensing or registering loan originators, the reference to a "mortgage licensee" in the Mortgage Call Report provision is intended to mean only licensed loan originators.

In other words, there is no statutory basis under the SAFE Act to extend the Mortgage Call Report provision to requiring each mortgage company to submit a quarterly financial statement and a quarterly report to each state on its mortgage activity in the state. A state regulator may already have or seek authority under its state law to require licensees to submit quarterly financial statements and loan activity reports, but the authority itself does not exist under the SAFE Act.

The upshot, from the industry's perspective, is that a Mortgage Call Report will impose significant operational and financial obstacles.
For instance the National Association of Mortgage Brokers (NAMB) believes there are "several legal flaws" in the proposal; and, it is also concerned about the burden of such reporting on small business mortgage companies, and places an "unacceptable financial burden" on small businesses.

If you have any questions about this NMLS requirement or would like assistance with mortgage compliance, please contact Jonathan Foxx, Managing Director or call 516-442-3456 x 100.

Highlights

Configuration

  • Quarterly report of condition
  • Submitted through NMLS by an entity with at least one licensed mortgage loan originator
  • Consists of two parts:

1. Part I: Residential Mortgage Loan Activity Report, by state.

2. Part II: Financial Condition Report for the entity

Policies

  • Executed by the company holding more than one license type in a jurisdiction is only required to submit one NMLS Mortgage Call.
  • Report for that jurisdiction. A company licensed in multiple states will complete a separate Residential Mortgage Loan Activity Report for each state in which they are licensed.
  • Companies not licensed in a state but employing state-licensed mortgage loan originators are afforded the opportunity by the state regulator to create a record in NMLS and submit the record to the state through NMLS.
  • Companies with one or more licenses in any "Approved" status will be required to file the NMLS Mortgage Call Report on a quarterly basis.
  • Failure to submit the report within 45 days of the end of the quarter will result in a "deficiency" placed on licenses or registrations held by the company and may result in a state regulatory action. Such deficiencies will prevent license or registration renewal.
  • Mortgage Call Report financial information must be reflective of the licensee's mortgage activities. Consolidated financial information will not be acceptable. Financial information should be reported on a Year-To-Date (YTD) basis.
  • Companies that, under state laws or regulations, are required to submit a self-prepared financial statement on an annual basis as part of maintaining a license or registration may use the Mortgage Call Report to meet this requirement.
  • Companies that are required to submit a Compiled, Reviewed or Audited financial statement must complete and submit such financial statements through NMLS in addition to the Mortgage Call Report.
  • Companies must submit quarterly residential mortgage loan activity data that reflects the company's operations within a state for each state in which they are licensed or registered through NMLS. All mortgage origination activity of their licensed mortgage loan originators must be included on the Mortgage Call Report. Activity is to be reported on a Year-To-Date (YTD) basis.
  • All company filings are confidential and will not be made public by NMLS, but will be available to state mortgage regulators under the system's information sharing architecture.
  • State, regional and national aggregated data is considered public information and may be made available by NMLS or state regulators.
  • The Mortgage Call Report is a "uniform form" that will be used by all companies, regardless of a company's organizational structure and activities. Companies will only be required to complete sections and questions that are relevant to the company's activities and/or authorities

Visit Library for Issuance

Law Library Image

NMLS Mortgage Call Report - Request for Public Comments
March 15, 2010